Showing posts with label Investment. Show all posts

Tuesday, 7 July 2020

7 financial decisions you need to make before you turn 30

7 financial decisions you need to make before you turn 30

7 financial decisions you need to make before you turn 30

It is never too early to plan your finances. So, if you are in your 20s or turning 30. It is the right time to make important financial decisions of your life. It is very important to start saving for your future needs at the right time and age. The decisions you take at this stage will impact your financial security later in your life. 

A financial plan should be followed to build a strong financial base to secure your future life. This phase of life is the right time to put in all your efforts to achieve your major financial goals to lead a comfortable life after retirement.


When you grow older, some financial products become more expensive or even few products became inaccessible. Other than this advantage, saving early would ensure you have a greater number of years to invest and it will compound to many times by the time you retire. 

There is an old saying that – it is never too late to follow your dreams and there is no time like the present to start. In this post, let’s look at the financial decisions you need to make before you turn 30.


Here are 7 financial decisions you need to make before you turn 30

You need to take the following 7 financial decisions before you turn 30 so that you can lead a comfortable life after your retirement.

1. Save money for retirement

Start planning for your retirement when you are in your 20s or at least before you turn 30. You may argue that there is ample time to plan retirement, but as per experts this is the right age to prepare yourself for your retirement (the earlier the better). It is good to have enough money at the time of retirement, so you do not have to rely on your kids for your expenses. So, start investing and put some part of your income every month in a good and suitable retirement plan that will help you reach the target you have set for your retirement.


2. Save money to buy a home

Every one of us would like to own a place we call home. Even if you don’t want to buy a home for several years, you have probably started thinking about how to save for a down payment to buy a home. A down payment for a home makes it easier to qualify for a home loan. This is the perfect age, when you are young, energetic and can start saving your money to fulfil your future goals. Saving this money will help you be ready when the time comes and will also give you more purchasing power to find the perfect home of your choice in the area or locality that you want.

3. Get Insured

Life is uncertain and life insurance can provide financial help to your family when you are no longer around them. Nothing can replace a loved one but advance planning with life insurance can make things easier for those you leave behind. The earlier you buy a life insurance, the lesser the premium amount you need to pay. So, secure your family's future today and make term insurance your best friend. And do not stop with just life insurance cover. With rising medical expenses, you also need to buy a health insurance to cover you and your entire family. Health insurance policy provides financial cover to individuals for any unforeseen medical emergencies, be it an illness or an accident that has led to hospitalization.

4. Build an emergency fund

Future is uncertain, and no one can predict the future. So, you should set aside at least six months’ worth of expenses in a separate emergency fund for emergencies. The size of emergency fund varies according to individual needs and circumstances. While building an emergency fund, you also need to consider your existing EMIs and insurance premiums that need to be paid regularly. The habit of building an emergency fund will make your life easy and you can tackle any financial emergencies easily. However, you have to make sure that you do not withdraw from this fund unless it is for emergencies.

5. Make a clear direction of your career

By the time you hit 30, you would have changed a couple of jobs. Your job/work is your financial asset, and the one that generates the income for you. By the age of 30, if you are not well settled in a job/work, you have to do some soul searching. You should also know what makes you happy and helps you to generate the income. If you are satisfied, then stick to it and follow a routine investment plan that will help you reach the financial targets you have set for yourself.

6. Save for your children’s education & marriage

Even if you are single, it is important for you to start planning for children’s education & marriage as early as possible. You should have a rough child investment plan in mind to financially secure your child’s future. Since the cost of education increasing every day, you need to plan for your children education in your 20s only. Make sure you set a separate investment plan for your children’s marriage.


7. Invest in yourself

Investing in yourself is one of the best returns on investments you can have. Do not stagnate but continue to increase your income by investing in yourself. Develop new skills so that you get a promotion in your current job. Keep learning new techniques and keep your skills sharp. That way you will always justify your promotions and remain valuable to your organization.

Making the right financial decisions in your 20s will take you on the path of financial security. So, start from today and build a strong financial foundation for your future life.

You may also like to read: Money Saving Tips
You may also like to read: Benefits of Investing in Mutual Funds


You may also like to read: 7 Habits that can make you rich
You may also like to read: How to start a SIP?

If you liked this post, share it with your friends and colleagues through social media. Your opinion matters, please share your comments.

7 financial decisions you need to make before you turn 30


Tuesday, 23 June 2020

7 Investments for Tax Free Income in India

7 Investments for Tax Free Income in India

Everyone wants to save tax and that is why all of us want tax free income. In fact, there is a need to look at various investment options that offer tax free income in India. Tax planning is not a bad thing even the government itself has given many ways to save tax. There are various investments that offer return without any tax, but, in some cases, you can also get tax exemptions under sec 80C of the Income Tax Act, 1961. Therefore, I have compiled a list of investment options for tax free income.


Tax Free Income

Tax free income is the income received but not subject to income taxes. Any profit from investments is considered as the earning and the same profit is added to the taxable income. But there are many investments which are not taxable at the time of maturity. The profit from these investments is not added to the taxable income. Income received from these investments is called tax-exempt income.


7 Investments for Tax Free Income in India

Here are 7 investment options for tax-exempt income in India

1. Interest in Saving Account

The saving account is the basic type of saving scheme. You can open your saving account at any bank or post office. On your saving bank account, you normally earn 4% interest. But there are some private banks where you can get up to 6% interest rate on your saving account. The interest on your saving bank account (either banks or post office) up to Rs 10,000 is tax-exempt under section 80TTA from 2013 onwards. Any excess interest on your saving account is taxed at the rate of your income slab.


2. EPF Account

EPF (Employees Provident Fund) is a retirement benefits scheme managed and overseen by the Employees Provident Fund Organisation (EPFO). This scheme is mandatory for the employee of the private sector. The EPF account gives you all round benefit. You will get tax exemption on the deposit made in the EPF account under section 80C. You also earn interest on your EPF account which is higher than the bank fixed deposit or any other government saving scheme but this interest earning is tax-exempt. There is no tax on maturity amount of EPF. However, in case of withdrawal happens before 5 years, it’s fully taxable.

3. PPF Account

PPF (PublicProvident Fund) account is a popular retirement saving scheme and open for the general public. It is one of the best long-term investment schemes with salaried as well as the self-employed class of individuals in India. A PPF account can be opened by resident Indian individuals at any nationalized authorized bank, select post offices and specific private banks across India. Your deposits made in the PPF account are eligible for the deduction under section 80C. PPF offers an attractive interest rate and interest earned on deposits is tax-exempt. The full maturity amount is also exempted from tax. This makes the PPF account one of the most popular saving instruments.

4. Life Insurance Policy

The life insurance policy also gives you tax benefits. You can take a life insurance policy from LIC (Life Insurance Corporation of India) or any private life insurance company. The amount of premium paid for a life insurance policy is eligible for the deduction under section 80C.
The maturity amount of life insurance policy is also tax-exempt. This benefit is applicable only for those insurance policies whose sum assured is at least 10 times to the annual premium. You cannot expect high returns from insurance plans as insurance plans are not pure investment products.

5. ULIP (Unit Linked Insurance Plan)

A ULIP is a combination of life insurance along with investment. ULIP plan provides life cover and investment in different funds for meeting long term goals. ULIPs are suitable for long term investment horizon to achieve your long-term financial goals. These financial goals could be children’s higher education, children’s marriage, retirement planning, etc. The lock-in period for a ULIP is 5 years but you can have a ULIP with a duration of 10 or 20 or more. The returns out of the policy are completely tax-exempt.


6. Sukanya Samriddhi Account

Sukanya Samriddhi Account (SSA) is a Government-backed saving scheme targeted at the parents of girl children. The government gives the highest interest rate on this scheme. This scheme is a must if you have a girl child at home. The scheme is aimed at the betterment of girl child in the country. The account can be opened at any of the authorized banks or at any post office. Deposits made in this scheme are exempted from income tax under section 80C. The maturity amount and annual interest of this scheme are also tax-exempt.


7. Tax Free Bonds

These bonds also give you return without any tax. Generally, these bonds are issued by Government-backed entities. Some of the public undertakings issue these bonds are IRFC, PFC, NHAI, HUDCO, REC, NTPC, NHPC, IREDA, etc. The maturity period of these bonds is 10 years or more. However, such bonds get listed on NSE / BSE after some time and you can sell and buy these bonds even before their maturity. The maturity amount and interest received is your tax free income. These bonds can’t give you a higher interest rate than the government bonds.

Also read: How to start aSIP?


If you liked this article, share it with your friends and colleagues through social media. Your opinion matters, please share your comments.
7 Investments for Tax Free Income in India


Tuesday, 19 May 2020

What is Atal Pension Yojana (APY)?

What is Atal Pension Yojana (APY)?

Atal Pension Yojana (APY) is a guaranteed pension scheme for the citizens of India, focused on unorganized sector workers such as maids, drivers, gardeners etc. This scheme was launched by the Government of India in June 2015. 

The scheme aims to help weaker section to save up money for their old age while they are working and get a guaranteed monthly pension post-retirement. In this post, let’s take a look at the features and eligibility of Atal Pension Yojana (APY).


Atal Pension Yojana (APY)

The scheme is administered by the PFRDA (Pension Fund Regulatory and Development Authority) through the National Pension System (NPS).

 Under this scheme, a fixed guaranteed minimum pension of Rs. 1,000/-, 2,000/-, 3,000/-, 4,000/- and 5,000/- per month will be given on attaining the age of 60 years. 

The pension will be determined based on your age and the contribution made by you.


Features of Atal Pension Yojana (APY)

1. Under APY, there is a guaranteed monthly pension ranging from Rs 1000 to 5000 per month to the subscriber on attaining the age of 60 years.
2. The benefit of minimum pension would be guaranteed by the Government of India.
3. The government of India will also co-contribute 50% of the subscriber’s contribution or Rs. 1000 per annum, whichever is lower, for a period of 5 years who joined the scheme in the period June 01, 2015 to March 31, 2016.
4. Government co-contribution is available for those only who are not covered by any Statutory Social Security Schemes and is not the income tax payer.
5. All bank account holders can join Atal Pension Yojana (APY).


Eligibility criteria for Atal Pension Yojana (APY)

You need to fulfill the below-mentioned requirement to avail benefits from the Atal Pension Yojana (APY):
1. All citizen of India between the age of 18 to 40 years.
2. The applicant must have a valid savings bank account / open a savings bank account.
3. Aadhaar will be the primary KYC but it is not mandatory to provide Aadhaar number for opening an APY account.
4. Aadhaar and mobile number are recommended to be obtained from subscribers at the time of opening the APY account. If not available at the time of registration, Aadhaar details may also be submitted at a later stage.
5. The minimum contribution that anyone has to do is at least 20 years.

How to open Atal Pension Yojana (APY) Account?

Follow the below-given steps to open Atal Pension Yojana (APY) account
1. All nationalized banks provide Atal Pension Yojana (APY). Go to the bank branch where you have your savings bank account.
2. Fill the Atal Pension Yojana (APY) registration form and submit it to your bank.
3. Provide your Aadhaar / Mobile Number.
4. Ensure to keep the required balance in your savings bank account for the transfer of monthly contribution.
5. Some banks are also offering to enroll for APY through net banking facility.

Nomination in Atal Pension Yojana (APY)

It is mandatory to provide nominee details in Atal Pension Yojana Account. The spouse details are also compulsory wherever applicable. Their Aadhaar number is also to be provided.

Mode of contribution to Atal Pension Yojana (APY) Account

Contributions are to be remitted monthly through auto-debit facility from your savings bank account. The due date for monthly contribution will be as per the initial date of deposit of contribution into APY account.

Benefits of Atal Pension Yojana (APY) 

1. Under APY, there is a guaranteed monthly pension ranging from Rs 1000 to 5000 per month to the subscriber on attaining the age of 60 years, until the death of the subscriber.
2. After the death of the subscriber, the spouse shall be entitled to get the same amount of pension until the death of the spouse.
3. After the death of the subscriber and his/her spouse, the nominee will receive the entire pension money that the subscriber had accumulated till 60 years of age.
4. If the subscriber dies before 60 years, the spouse will have the choice to either exit from the scheme and claim the entire accumulated money or continue to maintain the account in subscriber's name for the remaining vested years. The spouse shall be entitled to receive the same amount of pension as the subscriber until the death of the spouse in the latter case.

Monthly Contribution in Atal Pension Yojana (APY)

Atal Pension Yojana is a periodic contribution based pension scheme. There is a guaranteed monthly pension ranging from Rs. 1000 to 5000 per month to the subscriber after their retirement at the age of 60. Your monthly contribution depends upon the amount of monthly pension you want and the age when you start your contribution.
Indicative APY Contribution Chart (Age-wise)
What is Atal Pension Yojana (APY)?


Penalty Charges in Atal Pension Yojana (APY)

Non-availability of the required balance in your savings bank account for the contribution in APY on the specified date will be considered as default. Banks can levy penalty charges for delayed payments as stipulated by the Government. Such penalty charges will vary from minimum Re 1 per month to Rs 10/- per month as shown below:
1. Re. 1 per month for a contribution up to Rs. 100 per month.
2. Re. 2 per month for contribution between Rs. 101 to 500/- per month.
3. Re 5 per month for contribution between Rs 501/- to 1000/- per month.
4. Rs 10 per month for contribution beyond Rs 1001/- per month.

In the case of discontinuation of payments of contribution shall lead to the following:
1. After 6 months the subscriber’s account will be frozen.
2. After 12 months the subscriber’s account will be deactivated.
3. After 24 months subscriber’s account will be closed.
Subscriber should ensure that the savings bank account to be funded enough for auto debit of contribution money. The amount of penalty will remain as part of the pension corpus of the subscriber.


Exit from Atal Pension Yojana (APY)?

1. Exit on attaining the age of 60 years: Exit from APY is permitted with 100% annuitisation of pension wealth. Monthly pension of Rs 1000 to 5000 per month to the subscriber, until the death of the subscriber. 

After the death of the subscriber, the spouse shall be entitled to get the same amount of pension until the death of the spouse. 

After the death of the subscriber and his/her spouse, the nominee will receive the entire pension money that the subscriber had accumulated till 60 years of age.
2. Exit Before attaining the age of 60 Years: Exit from APY before 60 years of age is not permitted. However, it is permitted only in exceptional circumstances i.e. in the event of the death of subscriber or terminal disease.


If you liked this article, share it with your friends and colleagues through social media. Your opinion matters, please share your comments.

What is Atal Pension Yojana (APY)?


Sunday, 17 May 2020

Pradhan Mantri Shram Yogi Maan-dhan (PM-SYM) | Features and Eligibility


Pradhan Mantri Shram Yogi Maan-dhan (PM-SYM) | Features and Eligibility


Pradhan Mantri Shram Yogi Maan-dhan (PM-SYM) | Features and Eligibility

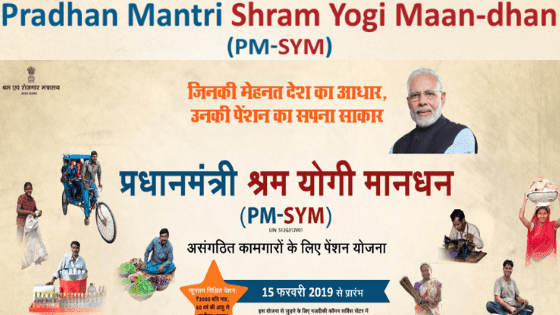
The Government of India on February 15, 2019 launched a pension scheme namely “Pradhan Mantri Shram Yogi Maan-dhan (PM-SYM)” for unorganised sector workers. This mega pension scheme was announced in the Interim Budget 2019. 

PMSYM is a voluntary and contributory pension scheme and the main motive of this scheme is to let unorganised workers save towards their retirement. The scheme has resemblance of EPF scheme for the employees in the organised sector. 

In this post, let’s take a look at Pradhan Mantri Shram Yogi Maan-dhan (PM-SYM) scheme.


Pradhan Mantri Shram Yogi Maan-dhan (PM-SYM) scheme

Pradhan Mantri Shram Yogi Maan-dhan scheme is a voluntary and contributory pension scheme. The PMSYM scheme is meant for old age protection and social security of unorganised workers. 

Under this scheme, the subscriber shall receive a minimum assured pension of Rs 3000/- per month lifelong on attaining 60 years of age at Common Service Centres (CSCs) across the country. 

If the subscriber dies, the spouse of the beneficiary shall be entitled to receive 50% of the pension as family pension. Please note that family pension is applicable only to spouse.


List of Unorganised Workers who can avail Pradhan Mantri Shram Yogi Maan-dhan (PM-SYM) scheme

Handloom workers, rickshaw pullers, domestic workers, street vendors, mid-day meal workers, brick kiln workers, cobblers, rag pickers, washer men, head loaders, home-based workers, beedi workers, own account workers, agricultural workers, leather workers, construction workers, audio-visual workers or in similar other occupations.


Eligibility for Pradhan Mantri Shram Yogi Maan-dhan (PM-SYM) scheme

Following category, people are eligible for Pradhan Mantri Shram Yogi Maan-dhan scheme.
1. Entry age should be between 18 and 40 years.
2. They should not be income tax payer.
3. Income should be Rs 15000 per month or below.
4. They should not be engaged in organised sector with membership of NPS, ESIC scheme or EPFO.
5. They should have a savings bank account or jan dhan account number with IFSC.
6. They should have Aadhaar number.

Features of Pradhan Mantri Shram Yogi Maan-dhan (PM-SYM) scheme

Following are the main features of Pradhan Mantri Shram Yogi Maan-dhan (PM-SYM) scheme.
1. Each subscriber shall receive a minimum assured pension of Rs 3000/- per month lifelong on attaining 60 years of age.
2. During the receipt of pension, if the subscriber dies, the spouse of the beneficiary shall be entitled to receive 50% of the pension as family pension. Note that family pension is applicable only to spouse.
3. If a subscriber has given regular contributions and died before the age of 60 years, his/ her spouse will be allowed to continue the scheme by payment of regular contribution or exit by receiving the beneficiary’s contribution along with interest as actually earned by the fund or at the savings bank interest rate whichever is higher.
4. PM-SYM is a contributory pension scheme on a 50:50 basis where contribution made by the subscriber is age specific and the equal contribution by the Central Government.  For example, if you enter the scheme at the age of 35 years, you are required to contribute Rs 150/ - per month till the age of 60 years an equal amount of Rs 150/- will be contributed by the Government of India.
5. The subscriber who has not paid the contribution continuously he/she will be allowed to regularize his contribution by paying outstanding dues along with penalty charges (if any).
6. Once you join the scheme, you need to contribute till 60 years of age. On attaining the age of 60 years, you will get the assured monthly pension of Rs.3000/- with the benefit of family pension, as the case may be.
7. In case you exit the scheme within a period of less than 10 years, your share of contribution only will be returned to you with savings bank interest rate.
8. If you exit after a period of 10 years or more but before superannuation age i.e. 60 years of age, your share of contribution along with accumulated interest as actually earned by the fund or at the savings bank interest rate whichever is higher.
9. If the beneficiary has given regular contributions and become permanently disabled before the age of 60 years, and unable to continue to contribute, his/ her spouse will be entitled to continue the scheme by payment of regular contribution or exit by receiving the beneficiary’s contribution along with interest as actually earned by fund or at the savings bank interest rate whichever is higher.
10. After the death of the subscriber as well as his/her spouse, the entire corpus will be credited back to the fund.

Contribution in Pradhan Mantri Shram Yogi Maan-dhan (PM-SYM) scheme

Your contributions to PM-SYM shall be made through ‘auto-debit’ facility from your savings bank account or jan-dhan account. You are required to contribute the prescribed contribution amount from the age of joining PM-SYM till the age of 60 years. Below chart showing details of entry age-specific monthly contribution is as under.
Pradhan Mantri Shram Yogi Maan-dhan (PM-SYM) | Features and Eligibility

Enrolment process for Pradhan Mantri Shram Yogi Maan-dhan (PM-SYM) scheme
Below is the step by step process to enroll for Pradhan Mantri Shram Yogi Maan-dhan (PM-SYM) scheme.
1. You need to visit neared CSC centre. Click here to locate the nearest CSC Centre.
2. While going to CSC for enrolment, carry with you the following:
a. Aadhar Card
b. Bank Account details along with IFS Code (Bank Passbook or Cheque Leave/book or a copy of bank statement as evidence of bank account)
c. Mobile phone for OTP verification
d. Initial contribution amount.
3. Village Level Entrepreneur (VLE) present at the CSC will key-in Aadhar number, name as printed on Aadhar card and date of birth as given in Aadhar card. Then it will be will be verified with the UDAI database.
4. Now details like your Bank Account details, Mobile Number, Email-id (if any), spouse and nominee details will be captured.
5. Self-certification for eligibility conditions will be done.
6. Now the system will auto calculate your monthly contribution payable according to your age.
7. You need to pay the amount of initial contribution under the scheme. VLE will generate a receipt for you. At the same time, a unique SYM number will be generated. The SYM Card will also be printed at CSC. Enrolment Form cum Auto Debit mandate will also be printed which will then be signed by you. VLE then scan the signed enrolment cum auto debit mandate and upload into the system.
8. With the completion of the process, you will get SYM card and a signed copy of enrolment form for your record.

Who will manage Pradhan Mantri Shram Yogi Maan-dhan (PM-SYM) scheme?

Pradhan Mantri Shram Yogi Maan-dhan scheme will be a Central Sector Scheme. It will be administered by the Ministry of Labourand Employment and implemented through Life Insurance Corporation of India and CSC e-Governance Services India Limited (CSC SPV). LIC will be the Pension Fund Manager and responsible for pension pay out.


Grievance Redressal for Pradhan Mantri Shram Yogi Maan-dhan

Customer Care number for Pradhan Mantri Shram Yogi Maan-dhan scheme is 1800 2676 888. This customer care facility will be available 24*7. Web portal/app will also have the facility for registering the complaints about Pradhan Mantri Shram Yogi Maan-dhan (PM-SYM) scheme.


If you liked this article, share it with your friends and colleagues through social media. Your opinion matters, please share your comments. 

Pradhan Mantri Shram Yogi Maan-dhan (PM-SYM) | Features and Eligibility


Tuesday, 12 May 2020

Rules of Investment | How much time does it take to Double, Triple or Quadruple your money


Rules of Investment | How much time does it take to Double, Triple or Quadruple your money


Rules of Investment | How much time does it take to Double, Triple or Quadruple your money

Personal Finances are personal for most of the people. There are a number of online guides and tips on how to manage your money. But most of the people find it difficult to understand these guides and tips due to their complexities. 

However, knowing some simple financial rules is very essential for you to understand when you can expect your investment to double, triple or quadruple. There are also some simple rules of investment that are evergreen. 

In this post, I will discuss some rules of investment and how much time does it take to double, triple or quadruple your money.


Rules of Investment

There are some simple calculations that you can apply to make intelligent investment choices. These evergreen rules of investment can do wonders for you and solve your basic financial problems in no time. 

So what are you waiting for just pick up a calculator and get started? Note that these rules of investment will give you an approximate of how much time does it take to double, triple or quadruple your money and a basis of comparing one investment to another. The actual final amount may vary after compounding.

Also read: Benefits of SIP | Advantages of SIP


Rules of Investment | How much time does it take to Double, Triple or Quadruple your money


1. Rule of 72

This rule tells you in how much time your invested money will double on compounding. Simply divide 72 with the rate of interest at which you are investing your money and it will give you the magical number which states number of years for your money to double in value. For example, your invested money will be double in 7.2 years if the rate of interest is 10% (72/10 = 7.2 years).

2. Rule of 114

The rule tells you in how much time your investment will triple on compounding. Similar to the rule of 72, just divide 114 with the rate of interest to know the magical number which states number of years for your money to triple in value. For example, it would take 11.4 years to triple your invested money if the rate of interest is 10% (114/10 = 11.4 years).


3. Rule of 144

Apply this rule when you want to know when your money will quadruple in value on compounding. Similar to the above rules, simply divide 144 with the rate of interest to know the number of years for your money to quadruple in value. For example, if the rate of interest is 10% then it would take 14.4 years to quadruple your money (144/10 = 14.4 years).

4. 100 minus your age rule

This is a rule of thumb used for asset allocation on the basis of your age. As per this rule, just subtract your age from 100 to find out the percentage of funds you should invest in equities. For example, if your age is 25 then according to the formula you should invest (100-25) 75% in equities and the rest in debt asset class.


5. 50 20 30 rule

The 50 20 30 is a general rule of budgeting to make sure you are on the right track. This rule is an easy tool that helps in creating balanced monthly budgets for self. According to the rule, 50% of the salary you should spend on essential living expenses like rent, food, clothes, transportation, bill payment and other expenses. The next 20% should go to short-term goals and maintain an emergency fund. The next 30% of your income should go to long-term financial investments. This rule will help you identify where you are overspending.

6. Future Value of your money

You should consider the inflation factor while investing your money for a long-term financial goal. With rising inflation, your purchasing power will be reduced in future. For example with an average inflation rate of 8%, an expense of Rs. 1 lakh will turn into Rs. 2 lakhs in 8 years. You can calculate the future value of your money with the help of below formula.
Future Value (FV) = Present Value (PV) (1+r/100)n
Here,
FV = Future value
PV = Present value
r = Rate of inflation (Annual)
n = Years to reach your goals

7. Emergency fund rule

You should put away at least six months worth of expenses in a liquid saving account for emergencies. You should also keep in mind your existing EMIs and insurance premiums while creating an emergency fund because that need to be paid regularly. Note that you should not withdraw from this fund unless it is for emergencies.


Hope after reading this post (Rules of investment), you can solve your basic financial problems and make intelligent investment decisions.


Also read: Money saving tips

If you liked this article, share it with your friends and colleagues through social media. Your opinion matters, please share your comments.

Rules of Investment | How much time does it take to Double, Triple or Quadruple your money